Elevated Properties Benefit Most From Reverse Mortgage Jumbo Loans
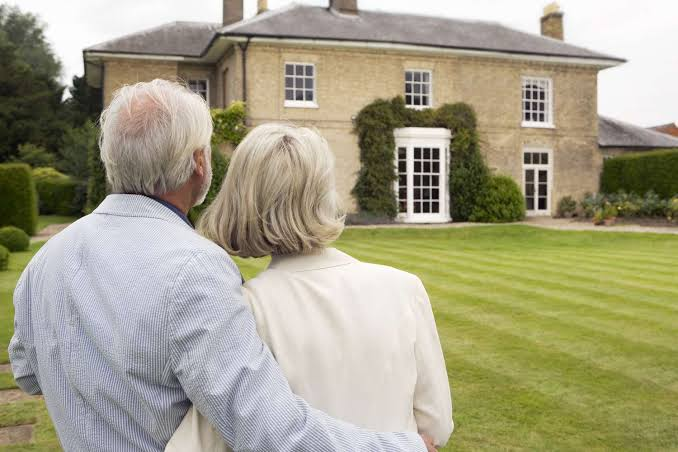
For many older homeowners, a house is more than a place to sleep. It is the keeper of birthdays, quiet mornings, and decades of hard-earned equity. And when that home sits in a high-value neighborhood or carries a price tag above traditional lending limits, the financial options can look a little different. That is exactly where reverse mortgage jumbo loans often enter the conversation.
These specialized loans are designed for borrowers with higher-value homes who want to tap into their equity without selling right away. For retirees who feel “house rich but cash careful,” this can be a meaningful option. If you are trying to understand whether a larger reverse mortgage solution fits your life, it helps to break things down clearly, calmly, and honestly.
Why a Jumbo Reverse Mortgage Matters for High-Value Homes
A traditional reverse mortgage has lending limits, which can leave owners of more expensive homes unable to access as much equity as they need. Properties that rise above those standard thresholds benefit from jumbo reverse loans. In simple terms, it allows homeowners with elevated property values to borrow against more of their home’s worth.
This matters because retirement does not always unfold according to a neat plan. Medical expenses can appear suddenly. Travel dreams may finally feel possible. Home updates may become necessary, not optional. A larger-value property may hold substantial wealth, but unless that wealth can be used, it may remain emotionally comforting yet financially untouchable.
Many families recognize this tension quickly. One homeowner once shared how her father would stand at the kitchen window every morning, coffee in hand, staring at the garden he planted 30 years earlier. He did not immediately recognize that the home he loved so deeply could also help fund the care and comfort he deserved. That moment hit hard. Sometimes the biggest financial resource is the one already surrounding you.
How Reverse Mortgage Jumbo Loans Work
At their core, reverse mortgage jumbo loans let eligible older homeowners convert a portion of their home equity into accessible funds. Unlike a traditional mortgage, monthly principal and interest payments are generally not required as long as you meet the loan obligations, such as living in the home, paying taxes, insurance, and maintaining the property.
The amount available depends on several factors, including your age, the home’s appraised value, interest rates, and the lender’s terms. Because these products are aimed at higher-value properties, they can provide larger loan amounts than standard reverse mortgage programs.
This can create breathing room in retirement. Funds may arrive as a lump sum, monthly payments, a line of credit, or a combination structure depending on the program. That flexibility is often one of the strongest benefits. You are not simply unlocking equity. You are potentially reshaping your retirement cash flow.
Still, this is a loan, not free money. The balance grows over time as interest accrues, and the loan is typically repaid when the borrower sells the home, permanently moves out, or passes away. That is why reviewing terms closely is essential.
Who Benefits Most From Reverse Mortgage Jumbo Loans
Not every homeowner needs this kind of financing. But owners of luxury, coastal, urban, or otherwise elevated properties often stand to benefit the most. If your home value exceeds the cap of a standard reverse mortgage, the gap between what you have and what you can access may be significant.
These loans can be especially helpful for:
– Retirees with substantial home equity but limited liquid savings
– Homeowners who want to age in place instead of downsizing
– Couples managing healthcare or long-term retirement expenses
– Borrowers seeking to preserve other investment accounts
– Families wanting more flexibility without selling a treasured property
There is also an emotional side to this decision. One couple once described their home as their “anchor,” but also their biggest piece of collateral in life. That word can sound cold, almost harsh, until you see what it really means here: a resource built through decades of discipline. In their case, using equity was not about surrendering something valuable. It was about finally letting that value serve them.
Important Factors to Review Before You Commit
Before moving forward, it helps to pause and assess the broader picture. A reverse mortgage tied to a high-value property can be powerful, but it should fit your goals.
Start with these questions:
– Do you plan to remain in the home for the long term?
– Can you continue to cover taxes, insurance, and upkeep?
– Have you compared lender fees, rates, and payout options?
– Have you discussed the impact on heirs or estate plans?
– Would another strategy, such as refinancing, downsizing, or using investments, better suit your needs?
Timing matters, too. Retirement planning has a way of filling every square on the calendar. A homeowner once laughed while showing a paper schedule pinned to the refrigerator with doctor visits, grandchild pickups, and home repair notes written in three different ink colors. Financial planning kept getting pushed down the list. That happens often. But when your home is your largest asset, making time to review your options can change the tone of your later years.
Key Advantages of a Jumbo Reverse Mortgage
For the right borrower, the advantages can be substantial.
First, you may access more equity than with standard programs. That is the headline benefit for owners of elevated homes.
Second, you can often remain in your home while using its value to support daily life, future expenses, or even unexpected emergencies.
Third, this strategy may reduce pressure on retirement accounts. Instead of drawing heavily from savings during down markets, some homeowners use home equity as a financial buffer.
Fourth, the structure can create peace of mind. There is something deeply reassuring about knowing the home you worked so hard to own can now work for you in return.
Of course, peace of mind grows best when paired with clarity. The more you understand the loan terms, the stronger your decision will feel.
Moving Forward With Confidence
High-value homes often hold hidden opportunity. When equity is substantial and traditional reverse mortgage limits fall short, these specialized loan options deserve careful attention. A jumbo reverse mortgage can open doors for homeowners who want to stay put, strengthen cash flow, and use their wealth more intentionally.
The key is not to rush. Ask questions. Review lender terms. Include family members or trusted advisors if that feels right. Most of all, remember that your home’s value is not just a number on paper. It reflects years of work, sacrifice, and memory.
For homeowners with elevated properties, reverse mortgage jumbo loans can offer more than financing. They can offer relief, flexibility, and a renewed sense of control at a stage of life when stability matters most.